Set yourself up for growth and success by focusing on your business and let me map out the bank path.
When commercial lenders say “No” or stall your loan, it is rarely a cash flow problem — it is a translation problem. I restructure your financial narrative into the data format lenders’ algorithms demand so you can unlock trapped equity, secure expansion debt, and protect your borrowing capacity.
Stop guessing. Start seeing. Take control of your story before the banks write it for you. Your accountant reports on history; I bridge the gap between how your business runs and the data your commercial lender needs to see.
Eidon Capital Readiness Tier 1 services examine your business and real assets from the perspective of the bank and give you straight talk on where you’re strong, weak and how you can improve within 48 hours of our meeting.
Following this, get your loan request package together in a timely and efficient manner with Eidon Capital Readiness Tier 2 services — this process will streamline your communication and time with a lender.
The common complaints/problems I solve:

My objective is to help business owners clearly see and realize their path to successful financing. Banks and lenders often seem overwhelming and confusing to small and medium sized businesses, but I am able to explain their needs and requirements in a way that simplifies the financing process and makes the requested documents easier to put together. I often say that the way a bank looks at risk is pretty much the same as how a good business owner looks at risk — we just have to translate the bank speak into your language.
I spent years in the banker's chair and as a business owner. I know exactly why banks tell you "No."
It usually has nothing to do with your revenue and everything to do with your Financial Architecture.
The Eidon Capital Readiness System bridges that gap.
I operate at the intersection of your internal data and lender requirements to help ensure you are perpetually bank ready and positioned for capital and growth.
Take control of your story before the banks start to write it for you.
Bank declines happen for a number of different reasons — I know them all. The most common decline when you feel your business is strong is because your Financial Architecture fails to translate your operational reality into their language of risk. It's a story gap. Here are a few more of the most common reasons for a no.

A rejection due to inconsistent cash flow narratives or improperly structured collateral follows you, tainting your internal risk profile for future requests. Too many poorly structured requests and lenders don't think you can change, even if you have. Lending is a small world, protect your reputation.

So often business owners try not to come across as 'greedy' or like they are "asking too much" but while a $100,000 here or there seems like a huge amount to you, it often doesn't matter to a lender. Banks have thresholds for types of requests, they would much rather you maximize your request within that threshold and not take all of the money than run out due to not asking for enough in the first place.

Applying when you're desperate and out of money triggers high-risk flags. Lenders focus on historical stability and forward-looking DSCR. They want to know you planned ahead and have some extra capital in case something unexpected happens without coming back to the bank.

Receiving a formal bank refusal — or even when you do secure new capital — you typically will not be able to borrow again for about 12 months. Why 12 months? This allows for the next year's financial statements to come in and enough time for banks to either see if you have been able to deliver on your promised plan or made the changes you had promised. Having the right financial architecture in place can allow for a multi-part borrowing plan or a bigger initial ask to set up for that rapid growth, big goal change.
Avoiding banks and self financing (aka bootstrapping) the business can significantly slow your business growth and reduce your profits.
Being scared of a bank is not a sound approach — let me explain the benefits and how to borrow successfully to maximize your potential.

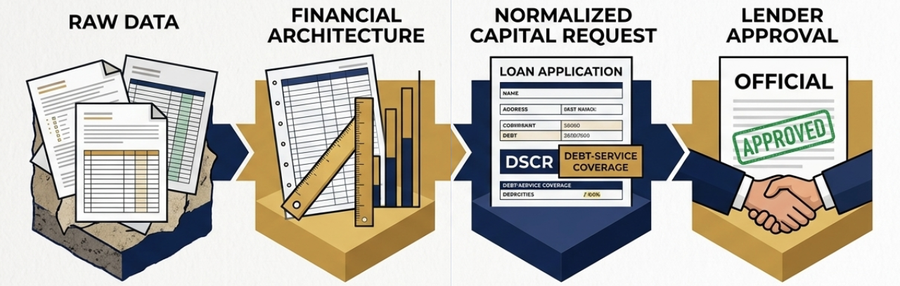
The path from operational data to lender-ready capital architecture.
Align your operational data and credit timing so you choose your lender, rather than the other way around.
Compress the time spent assembling your request package and clearing underwriting.
Optimize your debt structure to maximize your borrowing capacity while minimizing personal cash injection.
Have verified answers to the bank’s risk and debt-service questions before they ask them.
Free up operational bandwidth to grow stably, deploying debt at the exact right inflection points.
Architected for high asset volume, progress billings, retainage holdings, and complex work-in-progress (WIP) schedules.
Explore Construction & Real Estate PathwaysArchitected for scaling commercial operations, inventory cycles, equipment acquisition, and optimizing working capital capacity.
Explore Operating Business PathwaysMonthly masterclasses that train business owners on underwriter scoring algorithms to proactively fix credit hurdles before approaching commercial lenders.
The positive impact of financing.
In short, businesses perform better when they finance.
According to Statistics Canada's Survey on Financing and Growth of Small and Medium Enterprises, high-growth Canadian SMBs (those achieving over 20% annual sales growth) are significantly more likely to utilize structured debt financing — term loans, lines of credit, and commercial mortgages — to scale operations, invest in fixed assets, and enter new markets.
In contrast, over 34% of Canadian SMEs experience zero growth or declining sales, heavily driven by cash flow bottlenecks and under-capitalization. In the eyes of a bank, growth without structured financial architecture isn't expansion — it's risk.
Data from Innovation, Science and Economic Development Canada (ISED) demonstrates that while top-tier small businesses secure up to a 97% approval rate on requested debt capital, nearly 1 in 5 non-seeking businesses decline to apply — either out of perceived high costs or fear of rejection due to weak financial positioning.
BDC's Small Business Health Index tracks that Canadian firms maintaining clear credit visibility and intentional capital deployment maintain cash flow expectations that outpace non-borrowing peers by over 33%.
Data from Statistics Canada, Innovation, Science and Economic Development (ISED), and the Business Development Bank of Canada (BDC).
What's happening with business borrowing across Canada:
| Metric | 2024 | 2025 |
|---|---|---|
| Requested External Financing | 36% | 39% |
| Requested Debt Financing | 9% | 20% |
| Debt Financing Approval Rate | 89% | 97% |
| Required to Pledge Collateral | 66% | 75% |
| Use: Working/Operating Capital | 49% | 45% |
| Use: Debt Consolidation | 17% | 24% |
The overall provincial and national averages obscure the realities of who actually secures funding. A business's success rate in acquiring debt financing varies drastically based on its size and maturity:
Let's position your financing request with the same strategies and resources a medium enterprise has. Book Tier 1 now.
Did you know the Indigenous lending landscape has numerous additional options through their own lending facilities.
| Province/Territory | Micro (1–4) # | Micro % | Small (5–99) # | Small % | Medium (100–499) # | Medium % | Total SMEs | % Requested Financing |
|---|---|---|---|---|---|---|---|---|
| Alberta | 79,703 | 57.30% | 57,479 | 41.30% | 1,941 | 1.40% | 139,123 | 81.60% |
| British Columbia | 99,067 | 57.30% | 71,445 | 41.40% | 2,311 | 1.30% | 172,823 | 82.50% |
| Manitoba | 19,471 | 57.10% | 14,042 | 41.20% | 594 | 1.70% | 34,107 | 81.60% |
| New Brunswick | 11,769 | 57.20% | 8,487 | 41.20% | 325 | 1.60% | 20,581 | 77.00% |
| Newfoundland & Labrador | 7,336 | 57.30% | 5,290 | 41.40% | 172 | 1.30% | 12,798 | 77.00% |
| Nova Scotia | 14,469 | 57.10% | 10,434 | 41.20% | 417 | 1.60% | 25,320 | 77.00% |
| Ontario | 238,300 | 57.20% | 171,854 | 41.20% | 6,640 | 1.60% | 416,794 | 82.40% |
| Prince Edward Island | 3,048 | 57.20% | 2,198 | 41.30% | 79 | 1.50% | 5,325 | 77.00% |
| Quebec | 132,829 | 57.10% | 95,793 | 41.20% | 3,947 | 1.70% | 232,569 | 84.60% |
| Saskatchewan | 19,396 | 57.30% | 13,987 | 41.40% | 448 | 1.30% | 33,831 | 81.60% |
| Territories | 1,622 | 56.50% | 1,169 | 40.70% | 79 | 2.80% | 2,870 | 82.50% |
This data proves that financing isn't just about survival; it's a structural pivot. By formalizing your Financial Architecture and aligning your operational metrics with lender expectations, you bridge the gap between 'micro-business' and the higher-performing business where capital is abundant and approvals are nearly certain.
Eidon helps you move into that category by translating your reality into the high-confidence language lenders require, ensuring you aren't just requesting capital, but commanding it.
Discover in 3 minutes if commercial lenders will approve your request on your terms, say no immediately, or leave you stuck in endless paperwork.
Please enter a valid email address.
Your email unlocks the Scorecard — your score and recommendations appear when you finish the quiz. Heidi will follow up with capital-ready next steps. No spam. Privacy Policy.